Award-Winning Residential Property Damage Lawyers

30 Years of Experience Emblem

Residential Property Damage? Go Smart, GoSuits.

Request a free consultation. It takes about 60 seconds.

When disaster strikes your home, it can feel as though your entire life has been turned upside down. Whether it’s the aftermath of a fire, a destructive storm, or water damage, your home is more than just a building—it’s your safe haven. At a time when you’re at your most vulnerable, you count on your homeowners’ insurance to provide the protection you’ve paid for.

But what happens when your insurer makes the process difficult? When they deny your claim, underpay what’s needed to repair the damage, or delay payment altogether? Unfortunately, these challenges are all too common, leaving homeowners feeling frustrated and uncertain about their next steps.

First-party residential property damage claims are filed with your own insurance company for damages to your property caused by events like fires, windstorms, hail, or vandalism. Unlike third-party claims, where another party’s insurance is involved, first-party claims rely on the policy you hold with your insurer. This contractual relationship requires the insurer to uphold their obligations as outlined in the terms of your policy.

Hero Image
$1,900,000 Premises Liability
Litigated and Settled
$1,400,000 Premises Liability
Litigated and Settled
$1,000,000 Premises Liability
Litigated and Settled
$675,000 Premises Liability
Litigated and Settled
$450,000 Premises Liability
Litigated and Settled
TopVerdict.com - Top 100 Settlements Personal Injury 2023 - Sean Chalaki TopVerdict.com - Top 100 Settlements Personal Injury 2023 - GoSuits Trial Lawyers TopVerdict.com - Number Settlement - Collin County 2023 - GoSuits Trial Lawyers The National Top 40 Under 40 Trial Lawyers Attorney At Law Magazine - Law Firm of The Month Super Lawyers - Sean Chalaki - Rising Star - Personal Injury Litigation Sean Chalaki - The Best Lawyers in America 2025 Sean Chalaki - Best Lawyers: Ones to Watch 2021-2022

Reviews and Testimonials

30+ Years of Combined Experience

We have litigated thousands of cases and we have stood beside clients during some of the most difficult times in their lives. That experience helps us move quickly and confidently on your behalf as your residential property damage attorney.

No Attorney Fee Unless There Is a Recovery

You pay no attorney fee unless we recover compensation for you. Case expenses may still be owed. See how our fees work.

No Hidden Administrative Fees

Unlike some other firms that tack on unexpected administrative costs, we believe in complete honesty. Our pricing is fully transparent with no hidden fees, no surprise costs, and no fine print to worry about when working with our residential property damage lawyers.

Fast Response Time and Available 24/7

In residential property damage cases, the first 48 to 72 hours matter a lot. Failed appliance components get hauled off by remediation crews. Surveillance footage from nearby businesses gets overwritten. Carrier adjusters start building their file before you’ve had a chance to build yours. Call us at 2 a.m. Seriously. We’re up. Free consultations are open around the clock, and our intake team responds in minutes, not days. We answer in English, Spanish, Farsi, Arabic, Portuguese, Korean, Hindi, Tagalog, Urdu and Armenian, so you can explain what happened in your first language instead of waiting on an outside interpreter. The person who picks up can act, not just take a message.

No Attorney Fee Unless There Is a Recovery*

Start Your Free Case Evaluation

If you need immediate assistance, do not hesitate to call Residential Property Damage Lawyers!

Call Our Lawyer

What Is Covered Under Homeowners Insurance?
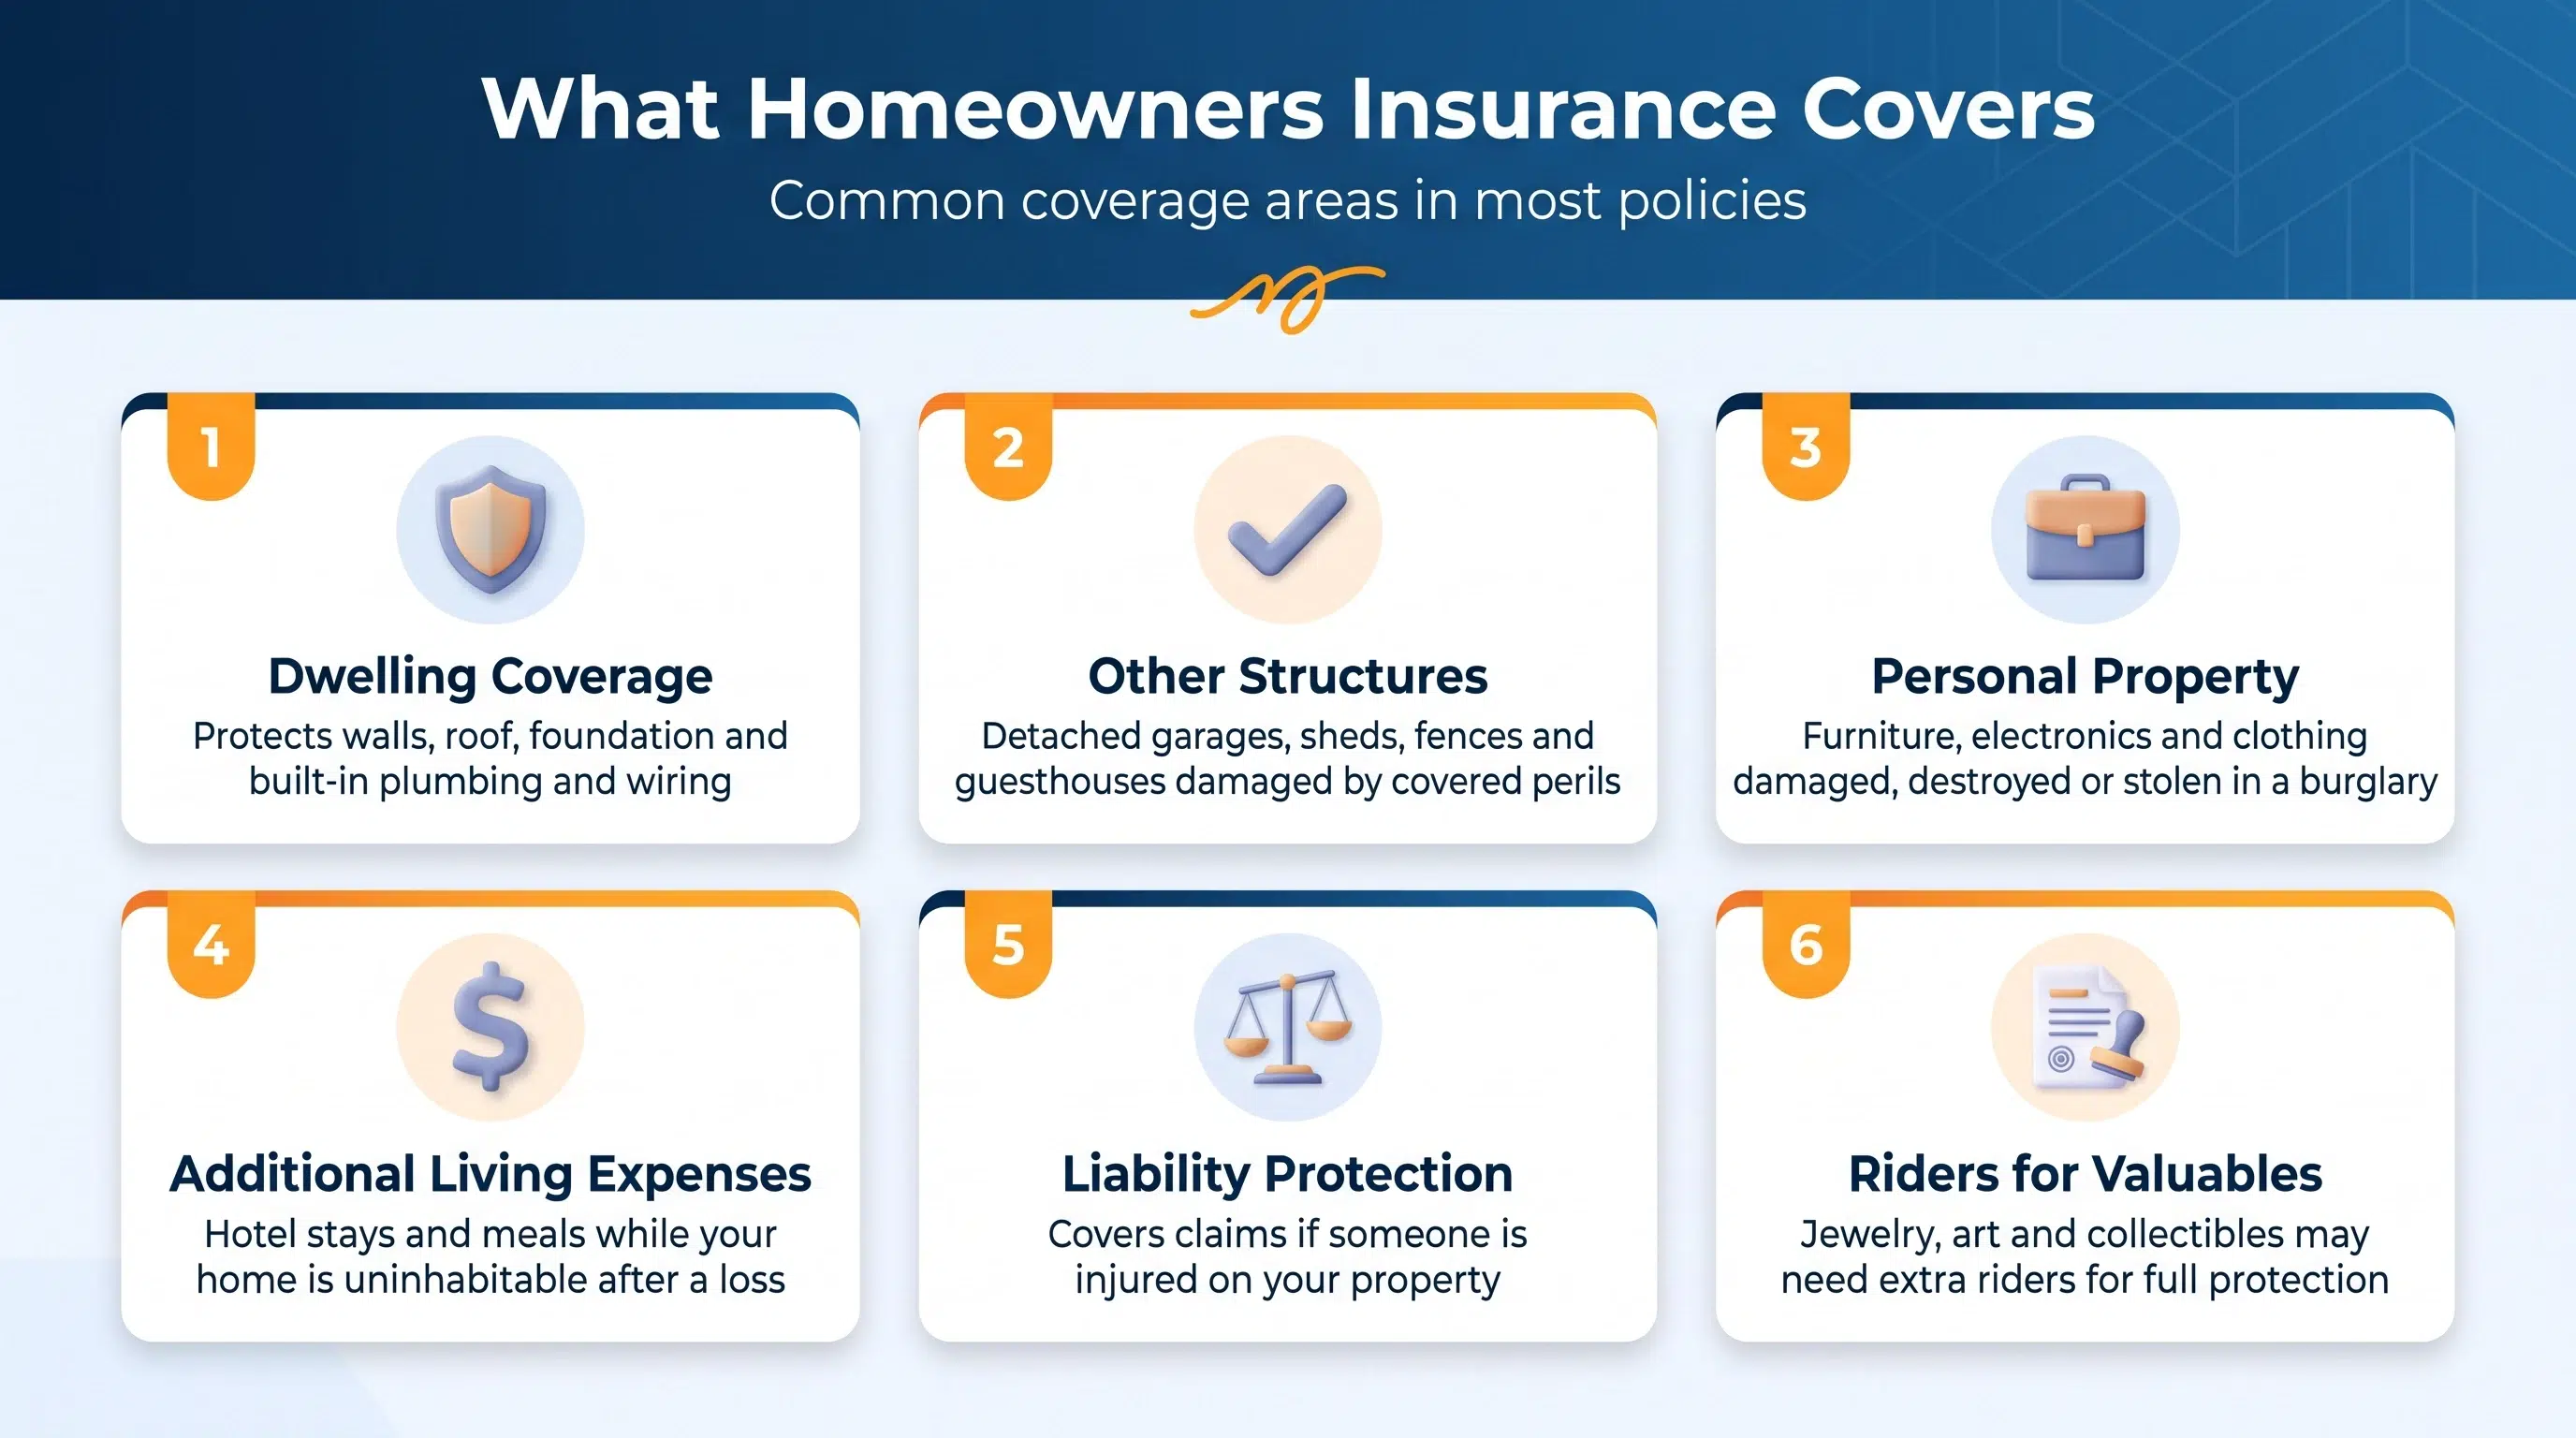
What homeowners insurance covers, from the dwelling and other structures to personal property, living expenses and liability

While each policy is unique, there are common types of coverage that most policies provide. Understanding what is typically covered—and the limitations—can help you better prepare for unexpected situations.

Typical Coverage Areas

  1. Dwelling Coverage:
    This portion of your policy protects the structure of your home, including the walls, roof, foundation, and built-in systems like plumbing and electrical wiring. Covered events typically include fire, windstorms, hail, lightning, and certain types of water damage. For example, if a tree falls on your roof during a storm or a fire destroys part of your home, the repairs or rebuilding costs may be covered under this section.
  2. Other Structures:
    Many policies also cover detached structures on your property, such as garages, sheds, fences, or guesthouses, if they are damaged by a covered peril. For instance, if a windstorm destroys a detached garage, your policy may cover the repair or replacement costs.
  3. Personal Property Coverage:
    This includes protection for your belongings, such as furniture, electronics, appliances, clothing, and personal valuables. If these items are damaged or destroyed by a covered peril or stolen during a burglary, your policy may reimburse you for their value. However, coverage limits may apply to certain high-value items like jewelry, art, or collectibles, so additional riders may be necessary for full protection.
  4. Loss of Use or Additional Living Expenses (ALE):
    If your home becomes uninhabitable due to a covered event, this coverage helps with temporary living expenses. For example, if a wildfire forces you to relocate, your policy may pay for hotel stays, meals, and other reasonable costs until repairs are complete.
  5. Liability Protection:
    Although not directly tied to property damage, liability coverage is a key component of most homeowners’ policies. It protects you against lawsuits or claims if someone is injured on your property or if you accidentally cause damage to someone else’s property.

Common Challenges Homeowners Face

Filing a first-party residential property damage claim can be a complicated and stressful process. Many homeowners encounter challenges that delay or reduce their ability to recover compensation for repairs. These challenges often include:

  • Denial of Claims: Insurers may deny claims based on technicalities, such as alleged maintenance issues or exclusions in the policy. These denials often leave homeowners feeling frustrated and uncertain about their options, specifically when the damage appears to be clearly covered by their policy.
  • Underpayment of Claims: Even when claims are approved, the amount offered may fall far short of the actual cost to repair or rebuild. Insurers often rely on low repair estimates or argue that partial repairs are sufficient when full replacements are needed, placing homeowners in difficult financial positions.
  • Delays in Processing: Insurers may slow the process by requesting unnecessary documentation, failing to respond promptly, or delaying payments. These delays can leave homeowners waiting months to make critical repairs, all while dealing with the ongoing stress and disruption caused by the damage.

When faced with these challenges, having an attorney by your side can make a significant difference. While insurance companies have extensive resources and teams of adjusters working to minimize payouts, your attorney serves as your advocate, working to protect your rights and ensure you are treated fairly throughout the claims process.

Preventative Steps Homeowners Can Take
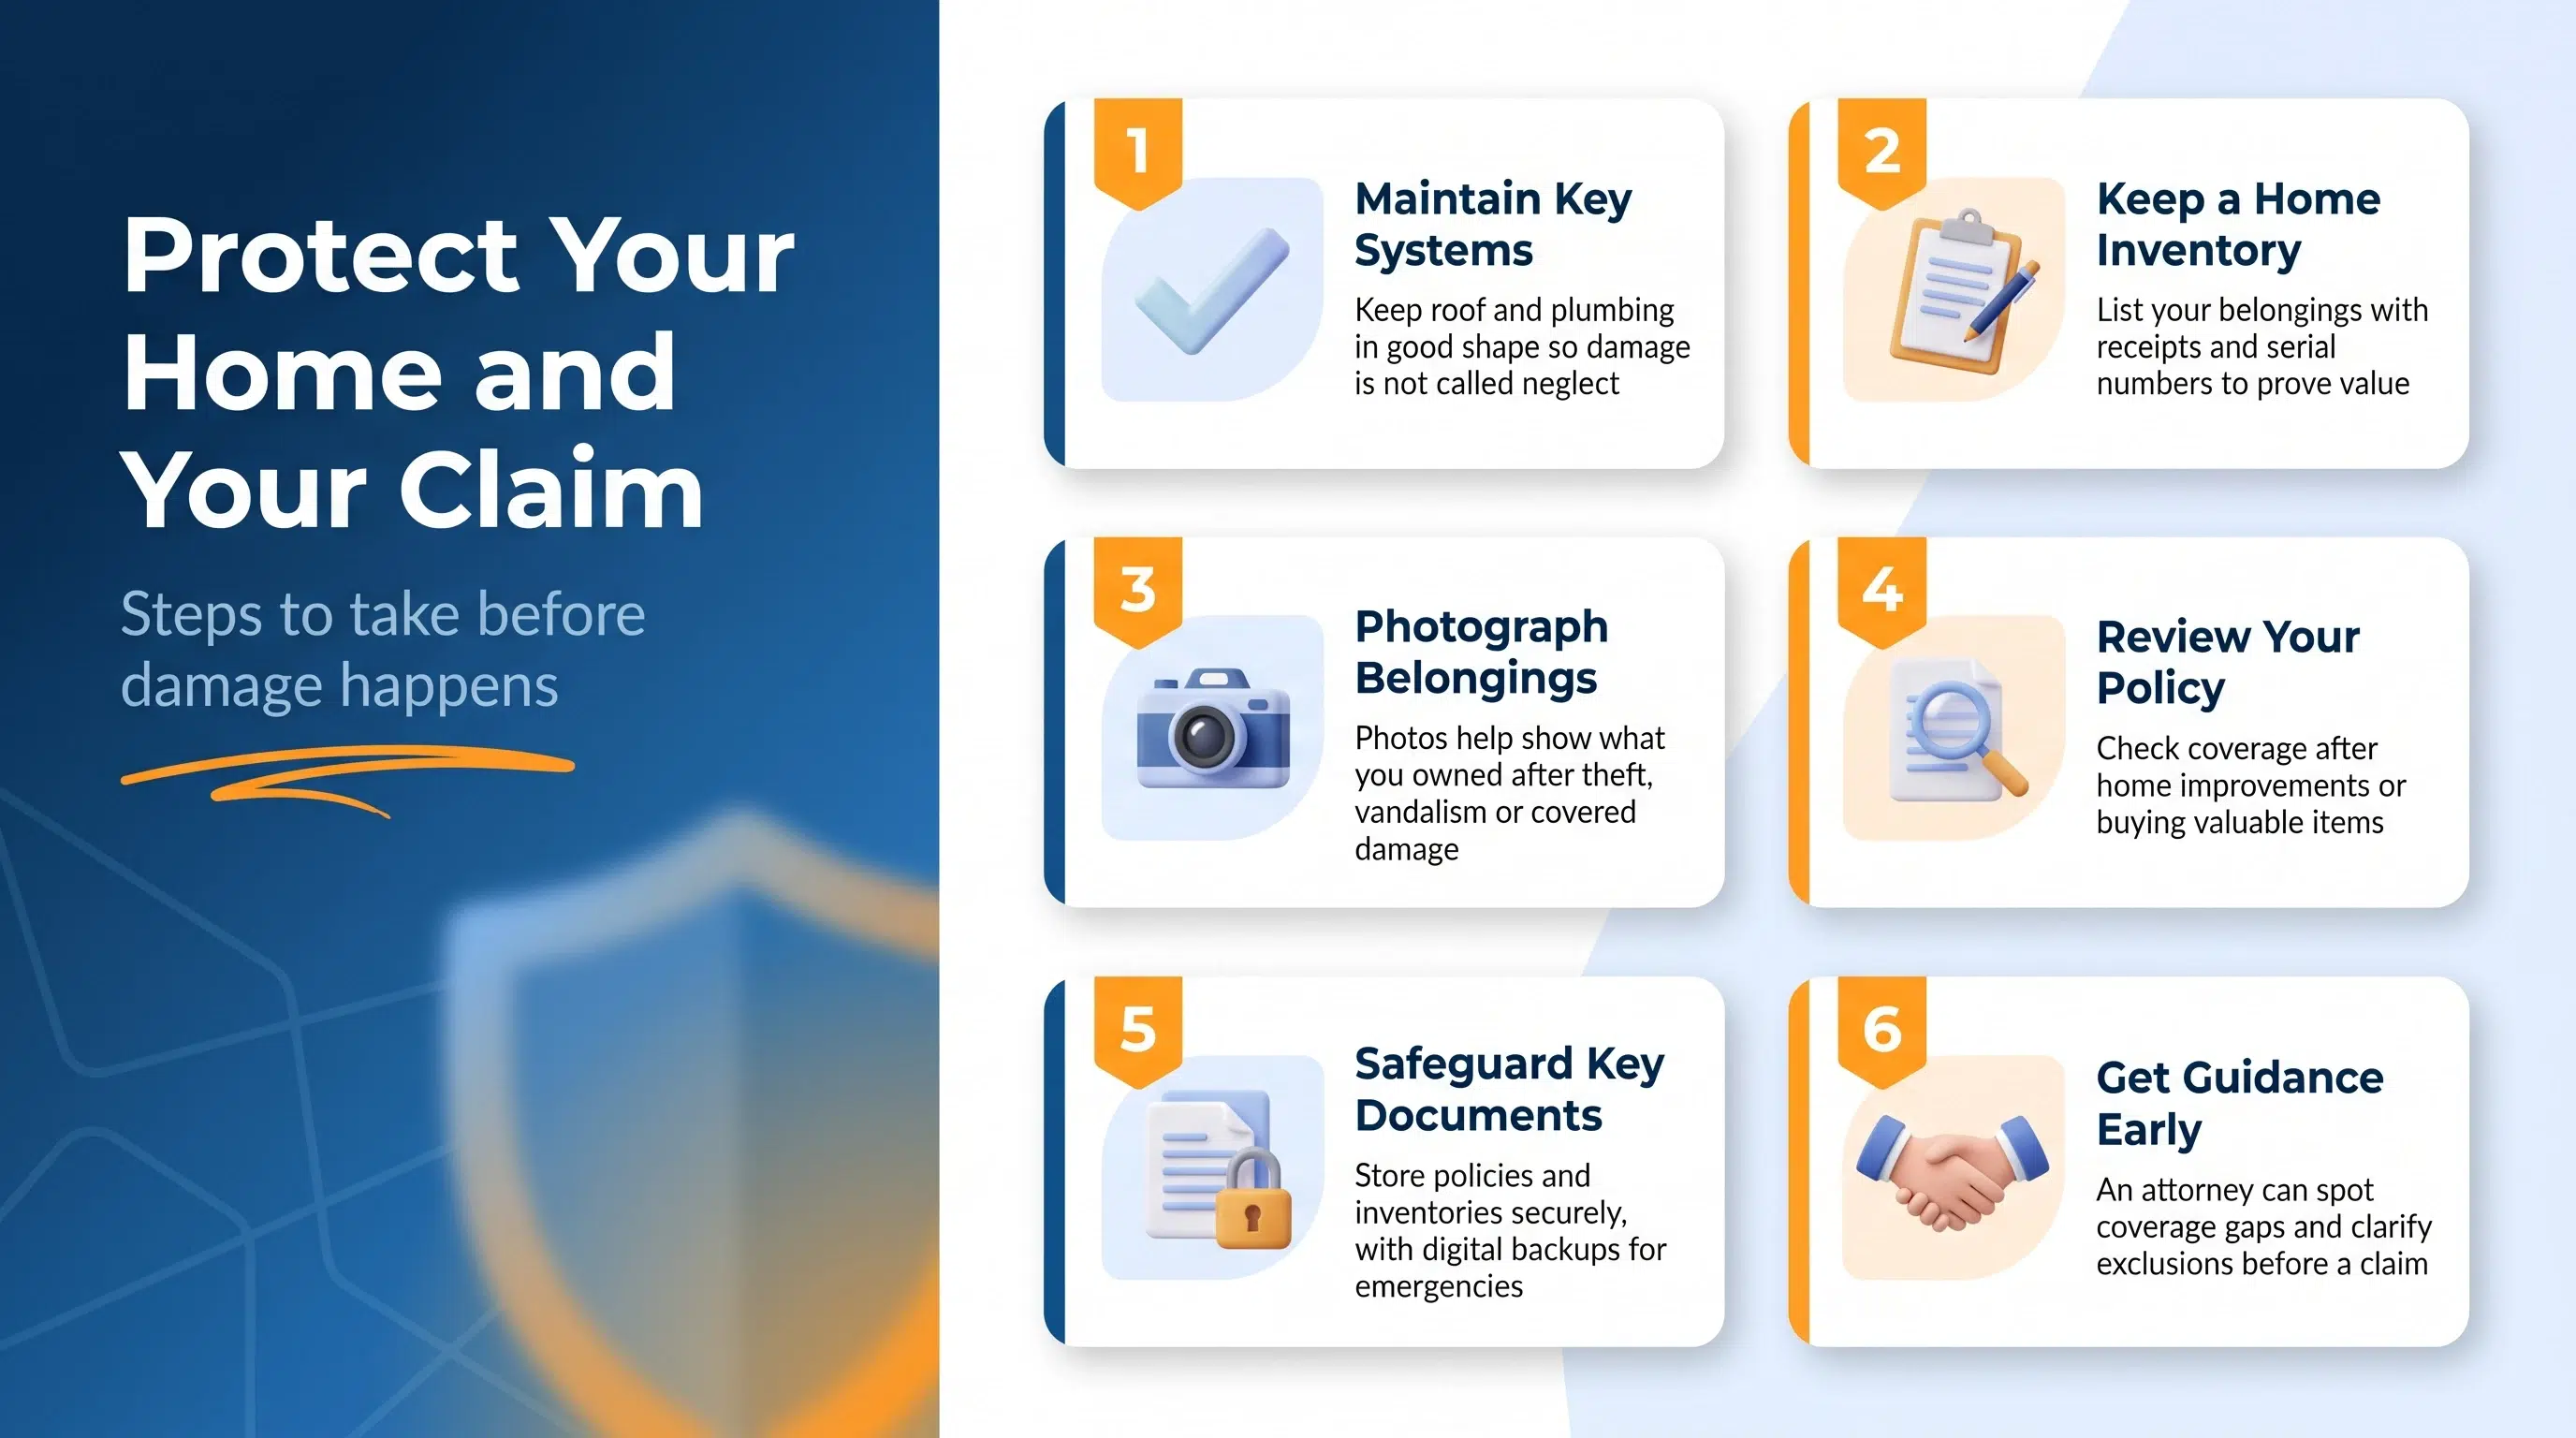
Steps homeowners can take before damage happens, from maintenance and a home inventory to reviewing the policy

  1. Perform Regular Maintenance: Keeping your roof, plumbing, and other key systems in good condition can prevent damage that insurers may try to classify as neglect or wear and tear, which is often excluded from coverage.
  2. Maintain an Updated Home Inventory: Create a detailed list of your belongings, including receipts, serial numbers, and photographs. This documentation helps prove the value of your items in the event of theft, vandalism, or covered damage.
  3. Review Your Insurance Policy Regularly: Periodically reviewing your policy ensures you have adequate coverage, particularly after home improvements or acquiring valuable items. Consulting with an attorney can help identify gaps in coverage and clarify exclusions.
  4. Safeguard Key Documents: Store insurance policies, home inventories, and property photos in a secure, easily accessible location. Digital backups are particularly helpful to protect these records from being lost or damaged during emergencies.
  5. Seek Professional Guidance Before a Claim: Consulting an attorney about your policy or potential risks can help you prepare for unexpected property damage and strengthen your position if a claim becomes necessary.
Get To Know Our Residential Property Damage Lawyers

It's time we do things the SMART way rather than the hard way
“Hire the Smart Suits for Your Lawsuits”

We'll Review Your Case - Free Consultation

(949) 989-5558

Residential property damage lawsuit steps and process

Step 1 of 9

Collect all available evidence after a residential property damage incident

Strong cases get built early. The first week or two is where most of the foundational work happens. Our attorneys pull together the homeowner or renter policy with all endorsements, fire marshal or police reports, every photo and video of the damage, repair estimates from licensed contractors, and whatever back-and-forth has already happened with the at-fault party or their carrier. We knock on doors, pull 911 transcripts when relevant, and if a defective product caused the loss, we secure the failed component before the remediation crew hauls it off. A sedan that ended up in a living room, or a slow slab leak in a condo, we don’t leave pieces behind.

Talk to a Lawyer. NO ATTORNEY FEE UNLESS THERE IS A RECOVERY*

Call Us Now

Frequently asked questions

How do I know if I have a valid residential property damage claim?

You may have a valid claim if your home was damaged because of someone else’s negligence, a defective product, a contractor’s mistake, or an insurer’s failure to pay a covered loss. Common examples include vehicle-into-structure crashes, contractor flooding, and appliance fires. To move forward, you need to show the responsible party’s conduct caused the damage and your financial losses. A free consultation with a lawyer can confirm whether your case meets your state’s legal requirements.

More Questions?

Call Our Lawyer

Written by GoSuits Team · Reviewed by Sean Chalaki, Attorney · State Bar of California No. 361185 · Jurisdiction: California, Texas and Illinois

How can I find a reliable residential property damage attorney near me?

Our Irvine Office

2082 Michelson Dr Suite 315, Irvine, CA 92612

(949) 989-5558

Open 24/7 for Emergencies

CONTACT US TODAY - 24/7 (949) 989-5558

Limited time to file your claim. Don't wait!

We’re here to help you get the compensation you deserve.

No Win. No Attorney Fees*

Start Your Free Case Evaluation